Why a 66% debut is attention, not proof
Tonbo Imaging India’s shares debuted at about a 66% premium to the ₹700 offer price on 23 October 2026, according to same-day market reporting. That is a strong listing-day signal, but it is still only a snapshot of early trading. It does not tell you whether the business will execute well over time, whether revenue will grow smoothly, or whether the company will convert its order book into cash on schedule.
This article is not investment advice and not a recommendation to buy, sell, or hold. It is a business and technology explainer for readers who want to understand what Tonbo actually builds, how it makes money, and what the prospectus says could go wrong.
What Tonbo actually builds
Tonbo describes itself as a global defense-electronics original equipment manufacturer (OEM) that designs sensing, processing, communication, and guidance systems for surveillance, reconnaissance, targeting, and control. In simpler terms, it builds the electronics and software that help defense platforms see in difficult conditions, process what they detect, and use that information to aim, track, or guide a system.
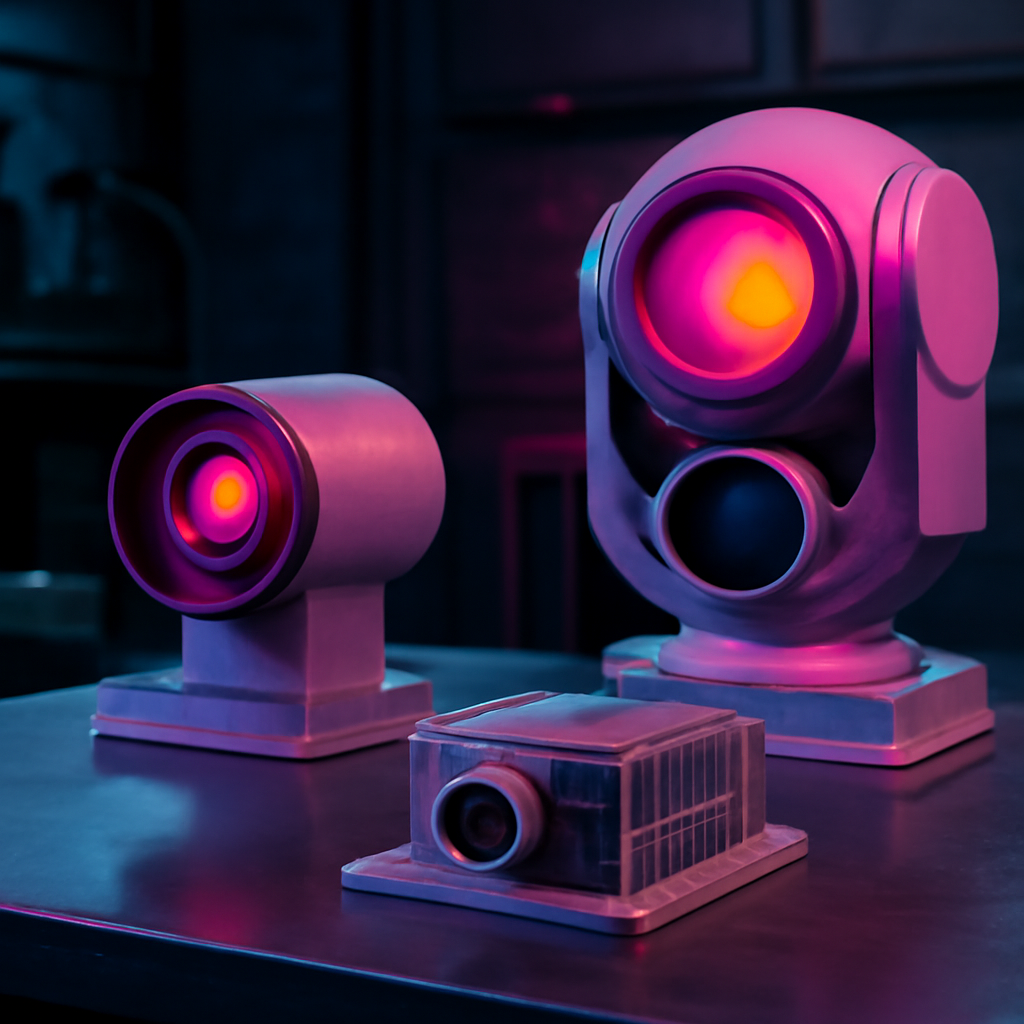
Its product set includes thermal-imaging cores, weapon sights, hand-held thermal binoculars, targeting systems, missile seekers, fire-control systems, and missile-guidance systems. These are not consumer electronics. They are specialized systems that must work reliably in heat, dust, vibration, low light, and high-stakes operational environments.
A useful way to think about Tonbo’s technology is as a stack. Electro-optical and infrared (EO/IR) sensing helps detect objects by using visible light, heat, or both. Thermal imaging can make a target or vehicle visible when normal cameras struggle, such as at night or in low-contrast conditions. Stabilization helps keep the image or aim steady when a platform is moving. Computer vision and embedded processing help interpret the sensor feed. Missile seekers and fire-control systems add the guidance and control functions that allow a platform or munition to track and engage a target.
That is why this kind of business is usually evaluated less like a fast-moving consumer brand and more like a defense systems engineer: the key questions are product qualification, reliability, customer approvals, export permissions, and the ability to deliver repeatably.
Compact verified facts
- Offer price: ₹700 per share; face value: ₹2.
- Offer size: 12,174,046 shares, entirely an offer for sale (OFS), aggregating ₹852.092 crore.
- The company receives no IPO proceeds, so the issue does not directly strengthen its balance sheet or fund expansion.
- Prospectus date: 19 October 2026; SEBI final prospectus listed on 22 October 2026.
- As of 30 June 2026, Tonbo said more than 28,000 systems had been deployed across 24 countries.
- FY2026 revenue from operations: ₹362.648 crore.
- FY2026 restated profit: ₹50.880 crore.
- Three months ended 30 June 2026: restated loss of ₹17.737 crore.
- Order book at 30 June 2026: ₹314.24 crore across 36 firm orders.
Seven prospectus checks
1) OFS means the company gets no IPO proceeds
The offer is entirely secondary. Existing shareholders are selling 12,174,046 shares, and the company itself does not receive fresh capital from the issue. That matters because an IPO can sometimes be a funding event for growth, debt reduction, or working capital. Here, it is not. The market is pricing the business, but the listing is not automatically improving its cash position or funding its next product cycle.
2) The model is IP-led, but manufacturing is outsourced
Tonbo says it uses proprietary in-house design and intellectual property, while manufacturing is outsourced to certified partners. This can be capital-efficient: the company can focus on engineering, software, product qualification, and customer programs without owning every factory asset itself. But that same model creates execution risk. It depends on supplier quality, production timing, component availability, and manufacturing discipline outside the company’s direct control.
In defense electronics, that trade-off is important. Outsourcing can improve flexibility, but it can also make delivery schedules more vulnerable if a supplier slips, a component is delayed, or a quality issue interrupts production.
3) The 28,000-deployment figure is notable, and the 94% export-volume claim needs careful attribution
The prospectus says more than 28,000 systems had been deployed across 24 countries as of 30 June 2026. That suggests a meaningful operating footprint and a long enough track record to have moved beyond a single-product story.
The document also says, citing Frost & Sullivan and customs data, that Tonbo accounted for 94% of India’s thermal-imaging export volumes by units shipped between FY2024 and FY2026. That is a striking number, but it should be read as a prospectus/third-party industry-report claim, not as an independently audited market-share fact. The right way to use it is as context for positioning, not as a guarantee of future dominance.
4) The order book is real, but so is execution and cancellation risk
At 30 June 2026, Tonbo reported an order book of ₹314.24 crore across 36 firm orders, split into ₹231.872 crore domestic and ₹82.368 crore overseas. An order book gives visibility, but it is not the same as recognized revenue. Contracts can be delayed, scope can change, and execution can slip.
The prospectus explicitly warns that order-book income may not be realized on time or at all. It also notes two cancelled contracts worth ₹28.083 crore in FY2025 and FY2026. That does not by itself imply a structural problem, but it does show why investors should separate booked demand from booked cash.
5) Government and tender concentration are material features of the business
FY2026 revenue from Indian government customers was ₹258.152 crore, or 71.19% of revenue from operations. That means Tonbo’s business is heavily tied to public-sector procurement and tender cycles. This is not unusual for defense suppliers, but it does create concentration risk. A large share of demand can depend on procurement timing, budget cycles, technical qualification, and contract awards rather than on steady consumer-like repeat purchasing.
That concentration does not mean the business is weak. It means the revenue path can be lumpy and dependent on institutional decision-making, which is exactly why investors should read the prospectus carefully.
6) Revenue seasonality, the FY2026 decline, and the quarterly loss need context
Tonbo’s FY2026 revenue from operations was ₹362.648 crore, and 78.61% of that was recognized in the second half of the year. That is a strong sign of seasonality in revenue recognition. It also means a single quarter can look unusually weak or strong depending on shipment timing and customer milestones.
Total income fell 22.02% from ₹474.390 crore in FY2025 to ₹369.939 crore in FY2026. At the same time, the company reported a restated profit of ₹50.880 crore for FY2026, while the three months ended 30 June 2026 showed a restated loss of ₹17.737 crore. The prospectus attributes part of that quarterly weakness to seasonality and lower revenue recognition. The key point is simple: do not annualize one quarter and treat it as a full-year forecast.
7) Security, supply-chain, inventory, and geopolitical risks are central here
The prospectus highlights several risks: short-term or non-recurring tender contracts, supplier concentration without long-term raw-material contracts, order delays or cancellations, classified-data security, outsourced manufacturing, export and geopolitical exposure, and working-capital or inventory pressure.
Inventory was ₹319.633 crore at 30 June 2026. The prospectus links that partly to a deferred export order and to supply-chain planning. That should not be reduced to a simple negative or positive. In a hardware business with long qualification cycles, inventory can reflect preparation for delivery as much as it reflects slow-moving stock. The important question is how efficiently those inventories convert into revenue and cash.
Geopolitics matters too. Defense electronics often cross borders in a world of export approvals, customer restrictions, and shifting procurement priorities. That can create opportunity, but it also creates uncertainty that a listing-day rally cannot remove.
Can you read Tonbo’s prospectus beyond the listing gain?
- 1) If an IPO is entirely OFS, what does the company receive from the issue?
- 2) What was Tonbo’s order book at 30 June 2026?
- 3) What share of FY2026 revenue from operations came from Indian government customers?
- 4) Why should the 94% thermal-imaging export-volume figure be attributed carefully?
- 5) Why should one weak quarter not be annualized on its own?
- A. Fresh capital for the company
- B. No IPO proceeds to the company
- C. A guaranteed cash reserve increase
- A. ₹314.24 crore
- B. ₹36.00 crore
- C. ₹852.092 crore
- A. 71.19%
- B. 28.81%
- C. 94.00%
- A. Because it is an independently audited market-share fact
- B. Because it is a prospectus/third-party industry-report claim, not an independently audited market-share fact
- C. Because it measures domestic government demand
- A. Because one quarter can reflect seasonality and lower revenue recognition
- B. Because every quarter has identical earnings power
- C. Because quarterly losses always equal full-year losses
Answer key: 1-B, 2-A, 3-A, 4-B, 5-A.
What would confirm execution after listing?
The next few disclosures matter more than the debut price. Readers should watch whether Tonbo converts the ₹314.24 crore order book into revenue on time, how the domestic-versus-overseas mix evolves, whether receivables and inventory move in a healthy direction, and whether cash collection keeps pace with shipments.
It will also be useful to see whether supplier resilience improves, whether product qualification and R&D cycles support repeat orders, and whether future exchange filings show stable execution rather than just periodic spikes. In a defense-imaging company, audited filings and delivery milestones tell you far more than one day of trading.
Risk and disclaimer
Informational article only. This is not investment advice, not a recommendation to buy, sell, or hold, and not a substitute for reading exchange filings. Verify facts in the SEBI-listed prospectus, company disclosures, and stock exchange updates. For personal investment advice, consult a SEBI-registered adviser.
Sources
SEBI final prospectus listing for Tonbo Imaging India Limited
SEBI red herring prospectus listing for Tonbo Imaging India Limited
Tonbo Imaging final prospectus PDF
Financial Express listing-day market report
Economic Times listing-day market report